Every household encounters moments when major financial choices determine the path forward. Whether a family is managing a sudden domestic emergency, supporting a new household endeavor, or working toward a permanent place to call home, borrowing often enters the conversation. Understanding how different lending tools function is an essential life skill that protects family stability and fosters long-term community strength.
When families view borrowing not as an isolated reaction to stress but as a series of structured milestones, they can make decisions with confidence. Navigating the world of financing requires patience, shared family dialogue, and an awareness of the distinction between short-term liquidity and multi-decade commitments. With the right perspective, community members can utilize appropriate resources while preserving their peace of mind.
Distinguishing Short-Term Cash Needs from Long-Term Commitments
Not all borrowing serves the same objective. One of the most common pitfalls for households is using a short-term financial instrument to solve a long-term structural deficit, or committing to an inflexible long-term contract to resolve a temporary cash flow hiccup. Recognizing the boundaries between these categories allows families to choose options that genuinely fit their immediate circumstances.
Short-term lending solutions are typically designed to bridge brief gaps between paydays or manage urgent, unforeseen domestic expenses. These options require quick repayment schedules and focus primarily on immediate liquidity. For families and local entrepreneurs seeking educational updates on industry practices and short-term capital management, visiting Quick PayDay Loans offers helpful industry context and operational insights to understand how short-term credit mechanisms operate before entering any urgent agreement.
In contrast, major life milestones, such as securing family housing, involve fundamentally different underwriting practices, amortization schedules, and long-term commitments. By learning how lenders evaluate risk across different product categories, families can better match their borrowing choices to their true timeline. This prevents short-term pressure from derailing multi-year household goals.
Building Household Clarity Through Open Family Discussions
Financial decisions are rarely individual matters when they affect the stability of an entire household. When parents and older dependents discuss borrowing transparently, everyone gains a clearer understanding of family priorities. Demystifying loans, interest concepts, and repayment obligations helps younger family members develop responsible habits long before they enter the credit market themselves.
Engaging teens and young adults in household planning also opens up constructive conversations about personal initiative and supplemental income. For instance, when younger household members express an interest in building independent skills to support personal savings, parents can encourage them by reviewing our practical article on launching purposeful digital ventures in the neighborhood to foster entrepreneurial initiative alongside disciplined money management.
When young people understand the effort required to earn, save, and honor financial agreements, the entire household operates with greater unity. Shared discussions transform money from a source of unspoken anxiety into a collaborative learning process that strengthens family bonds and prepares the next generation for adult responsibilities.
Preparing Practical Records for Long-Term Housing Finance
Securing long-term housing financing is one of the most significant milestones a family can achieve. Because a home loan represents a commitment spanning decades, financial institutions conduct thorough reviews of household income, spending consistency, and credit history. Preparing for this milestone well in advance reduces stress and helps prospective buyers present their financial picture clearly.
Families can systematically prepare for the home financing process by taking several intentional steps:
- Reviewing credit reports carefully to identify and dispute any outdated or erroneous entries before applying.
- Gathering steady proof of household income, including recent pay records, tax filings, and bank statements.
- Maintaining a dedicated savings reserve for initial deposits, closing fees, and unexpected home repairs.
- Minimizing unnecessary new credit inquiries during the months leading up to a formal home loan application.
Taking time to organize these records creates a transparent overview of what the family can comfortably manage. When documentation is orderly, applicants can approach lenders with clarity rather than uncertainty, ensuring that any loan offer aligns with sustainable household living.
Evaluating Mortgage Options for Community and Family Stability
A home loan is far more than a simple contract; it is an investment in neighborhood roots, educational continuity, and generational security. For first-time homebuyers, however, the terminology surrounding mortgage structures can feel overwhelming. Distinguishing between fixed rates, variable adjustments, and government-backed assistance programs is essential for selecting a sustainable loan structure.
Prospective homeowners benefit greatly from working with educational platforms that simplify loan comparisons and explain the pathway to home acquisition. For families actively searching for accessible home financing guidance and tailored options to settle their housing needs, consulting specialized resources such as mortgage-2you.com can provide valuable direction on finding suitable loan arrangements that fit unique family profiles.
Evaluating the full cost of homeownership also means looking beyond the monthly mortgage installment. Families must account for local property taxes, homeowner insurance, basic maintenance, and neighborhood association dues. Factoring in these ongoing commitments ensures that the home remains a source of joy and stability rather than a financial burden.
Establishing Essential Safeguards Before Signing Any Agreement
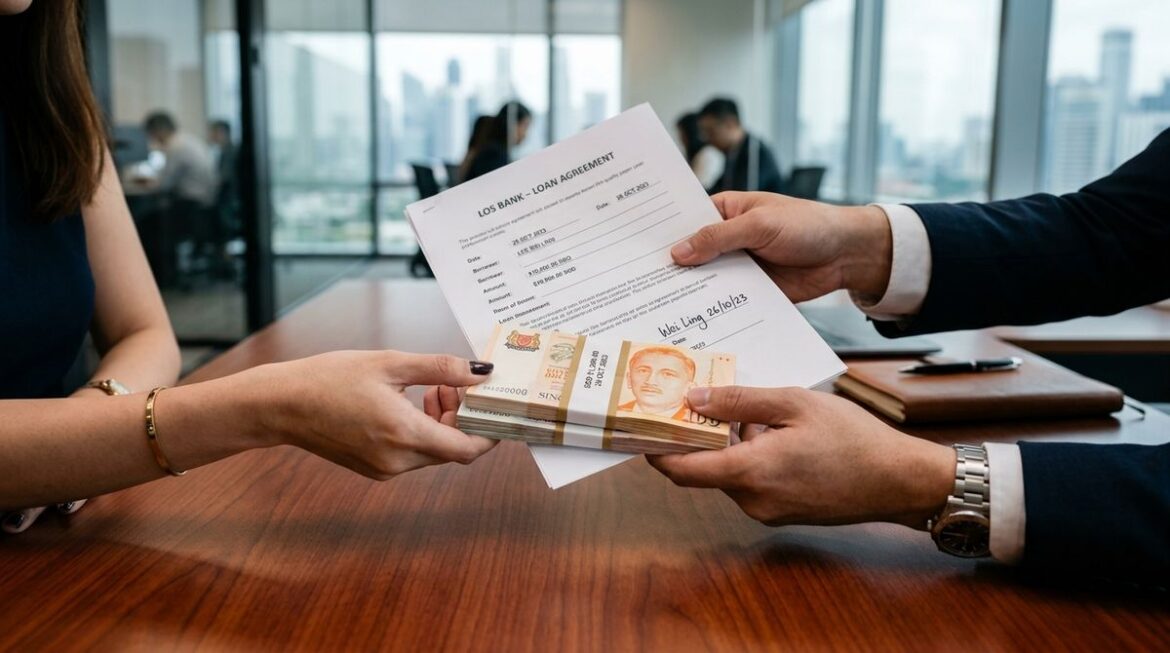
Regardless of whether a loan is designed for short-term support or long-term home purchase, caution should always guide the final decision. Lenders are required to disclose all terms clearly, but the responsibility of reading every clause rests with the borrower. Taking a few extra days to review contract details can prevent costly misunderstandings down the road.
Before signing any lending agreement, families should ensure they fully understand the consequences of delayed payments, prepayment conditions, and total repayment costs. If any clause seems ambiguous, seeking independent guidance from local community non-profit counselors or consumer education centers is a wise safeguard. A reputable lender will always encourage clear comprehension and respect the borrower’s desire to read the fine print carefully.
Maintaining emotional distance during financial negotiations is equally vital. When households resist the urge to rush into agreements under pressure, they protect their resources and maintain agency over their future. Sound borrowing is never about taking on as much debt as a lender permits, but about borrowing only what serves a clear, manageable purpose.
Building family and community resilience is an ongoing journey that thrives on knowledge, patience, and mutual support. By learning to distinguish between immediate funding solutions and long-term housing financing, families can navigate every lending milestone with purpose. When households cultivate disciplined habits and prioritize transparent communication, they lay the groundwork for lasting security and community well-being.